Still deciding?
Understand what lenders will evaluate before you apply.
Use the borrower journey and preparation tools to see what the request needs to support.
Before you apply
DON'T APPLY FOR AN SBA LOAN. YET.
The application is not where you want to learn how SBA loans get approved.
Before you hand your business plan, projections, and financial picture to a lender, learn what they will evaluate, what can weaken your application, and what you are putting at risk if you move forward.
Prepare Before You Apply · $199
SBA 7(a) + 504 · one year of access · 30-day refund · no automatic renewal
Already purchased? Go to Start Here.
PrepareLearn what lenders evaluate before the file is in their hands.
ProtectUnderstand working capital, commitments, and your exposure.
ApplyMove forward with more clarity about the application and the people reviewing it.
The mistake to avoid
Don't let the lender's questions be your first real look at the deal.
×The risky order
- Your business needs money.
- You find a lender.
- You submit the application.
- The lender starts asking questions.
- Now you discover what you were missing.
Wrong order.
✓Prepare first
- Your business needs money.
- You learn what lenders evaluate.
- You get the numbers and business story ready.
- You understand working capital and what you are committing to.
- You choose where to apply.
- You apply more prepared.
Prepare. Protect. Then apply.
What the lender is trying to understand
Before approval, four questions come into view fast.
You do not need to become an underwriter. You do need to understand the questions your application has to answer.
1
Can the business pay it back?
Get a clearer view of repayment, existing obligations, and the wider financial picture before someone else starts testing it.
Know whether the numbers deserve more work before you apply.2
Does your plan make sense?
Put the business story, projections, assumptions, and financing request in the same frame.
Find the gaps while they are still yours to fix.3
Will you have enough cash to run the business?
Look past the closing table and examine the operating cash the business may need after financing.
Getting funded should not leave the business starved for cash.4
Are you taking it to the right people?
Research lender and CDC activity, relevant experience, responsiveness, and fit before deciding where the file goes.
A lender search should be a decision—not a guess.The insight most borrowers never get in one place
The lender will tell you what they need. The Kit helps you understand what it means for you.
A good lender can explain the loan process. But the lender's job is to evaluate the financing. Your job is to understand the decision your business is making.
The lender asks for
Projections and financials
The information needed to evaluate the request.
You need to understand
Which assumptions are carrying those numbers?
What has to go right—and what deserves another look before you rely on it.
The lender evaluates
Repayment
Whether the financing appears supportable.
You need to understand
What does the payment do to the business?
Approval matters. So does what remains after the payment is made.
The lender reviews
Your wider financial picture
Obligations, relationships, and information relevant to the file.
You need to understand
What else can affect this request?
See the financing in context instead of discovering connected issues one question at a time.
The lender discusses
Structure, terms, and closing
The path required to complete the financing.
You need to understand
What are you committing yourself and the business to?
Know the questions to ask before the documents and deadlines start moving.
The lender moves toward
Approval and funding
The lending decision and transaction completion.
You need to understand
What happens after the lender says yes?
Funding is the beginning of living with the financing—not the end of the borrower experience.
A lender's job is to evaluate the loan. Your job is to understand the decision you are making.
The Loan-Ready Kit gives you the borrower view alongside the lending process.
See the system
This is what preparation looks like.
The Loan-Ready Kit connects the borrower journey, working tools, lender research, reference files, and a real SBA case study in one place.
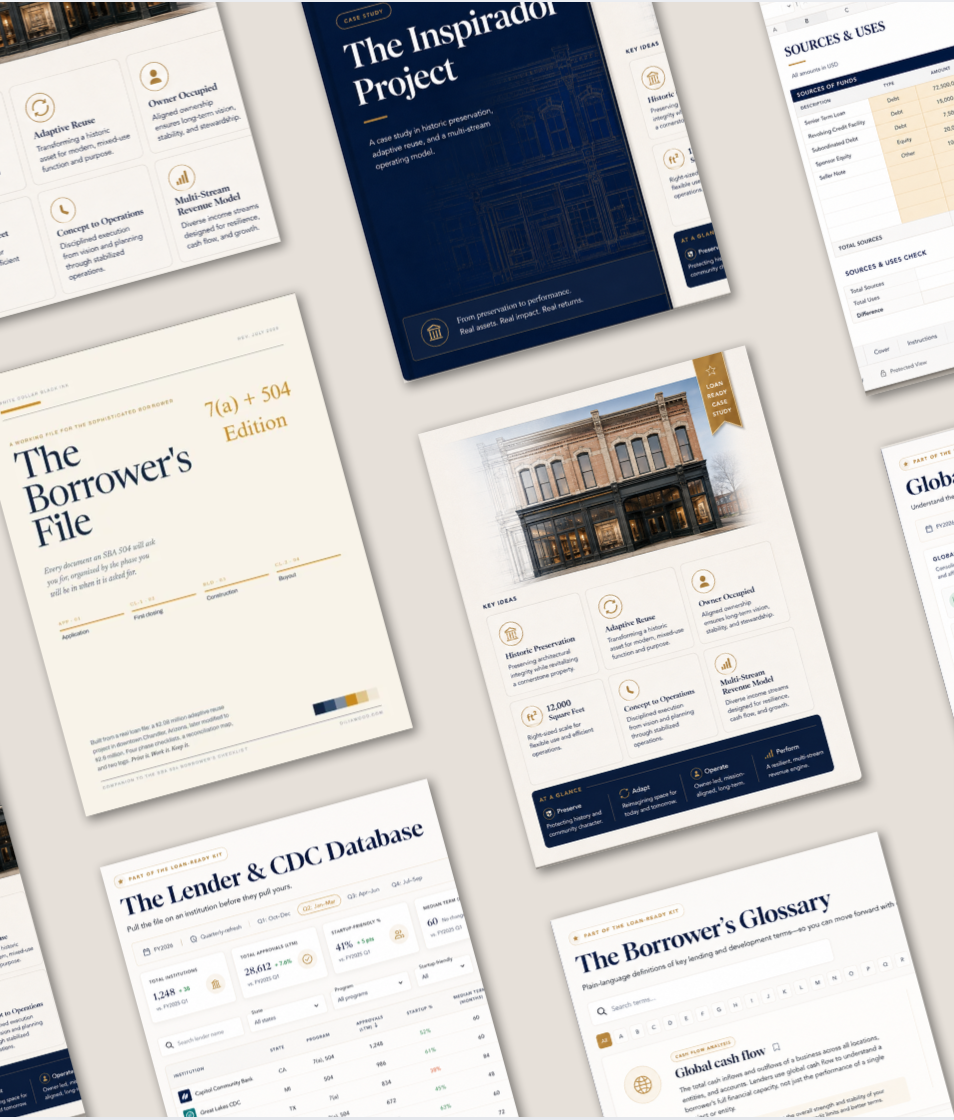
Actual Loan-Ready Kit product system. Use the journey in order or return to the tools as your financing process develops.
Approval is only part of the decision
What are you putting at risk if you move forward?
The goal is not simply to get through underwriting. It is to understand the financing well enough to protect the business and the investment you are making in it.
What happens to cash after closing?
What obligations are you taking on?
What assumptions have to go right?
What happens if the business underperforms?
What should you understand before you sign?

The Loan-Ready Kit
Everything I would want in front of me before applying for an SBA loan.
A self-paced borrower preparation system for SBA 7(a) and 504 financing.
1
Know what mattersStart with the borrower journey and understand what the application has to support.
2
Get the numbers togetherUse Working Papers plus Global Cash Flow and affiliation tools where relevant.
3
Protect operating roomWork through working-capital needs before funding becomes the only goal.
4
Choose the right peopleUse the Lender & CDC Database to research fit before you apply.
5
Then applyMove into the application with clearer numbers, stronger context, and better questions.
Built by a borrower
Dilia Wood
Experienced SBA borrower · builder · writer · educator
Built by someone who would use SBA financing again.
Dilia's firsthand SBA record includes a $2.6 million SBA 504 startup project approved 13–0 by the CDC loan committee. Approval was only the beginning: the borrower lifecycle continued through redevelopment, construction, working-capital decisions, operations, and transfer.
The Loan-Ready Kit turns that lived borrower experience into the preparation system she would want in front of her before applying—not after the financing process is already moving.
$2.6MSBA 504 project
13–0CDC loan-committee approval
IndependentNo lender referral compensation
What one year of access gives you
Start where you are. Come back when the financing changes.
You do not have to finish a course before the Kit becomes useful. Open Start Here, go to the decision in front of you, and return to the tools throughout your year of access.
1
DecideShould I pursue SBA financing?2
PrepareNumbers, story, working capital, people.3
ApplySubmit with a clearer understanding.4
UnderwritingQuestions, requests, review.5
ApprovalA milestone—not the whole journey.6
Close & fundUnderstand the commitments.7
OperateLive with the financing in the business.Approval is a milestone. It is not the whole borrower experience.
Building the application?
Work through the numbers, projections, and working capital.
Use the tools while there is still time to identify questions and strengthen the financing story.
Already talking to lenders?
Understand what they are asking for—and why it matters.
Use the Kit alongside the process to prepare questions, compare fit, and keep the borrower view visible.
Moving toward approval or closing?
Understand the decisions that continue after “yes.”
Return to working capital, obligations, and the operating realities that remain after funding.
For one year, the Kit stays beside you as the financing changes. Use the system in order—or go directly to the decision you are facing now.
Prepare before you apply
Give yourself the advantage before the application leaves your hands.
Understand what lenders will evaluate, prepare the financing story, protect operating room, and know what you are agreeing to before you commit.
$199
One year of access to the complete borrower preparation system
- Complete borrower preparation journey
- Working Papers
- Global Cash Flow & Affiliation tools
- Working Capital preparation
- Lender & CDC Database
- 7(a) & 504 Borrower's Files
- Inspirador Case Study
- Meaningful updates during access
- 30-day refund
- No automatic renewal
Already purchased? Go to Start Here.
Three things to know
Clear before you buy.
Is this a lender, broker, or loan application service?
No. The Loan-Ready Kit is an independent, self-paced borrower preparation system. Dilia Wood and White Collar Black Ink do not make loans, broker loans, package applications, or receive lender or CDC referral compensation.
Does the Kit guarantee SBA approval?
No. Lenders make lending decisions. The Kit helps you understand and prepare your own information before that review begins; it does not guarantee eligibility, approval, funding, rates, terms, or timing.
Who is this for?
Business owners preparing for SBA 7(a) or 504 financing—including working capital, equipment, expansion, business acquisition, owner-occupied property, and other eligible business needs—who want to understand the application and their own commitments before applying.
Your next move
Prepare first. Then apply.
SBA financing can be a powerful opportunity for a business. Treat the decision like one.
$199 · one year of access · 30-day refund · no automatic renewal
The Loan-Ready Kit is educational and informational borrower preparation. It does not guarantee approval, determine eligibility, or replace legal, tax, accounting, investment, financial-planning, lending, insurance, or other transaction-specific professional advice. Dilia Wood and White Collar Black Ink are not lenders, loan brokers, loan packagers, or CDCs and do not receive lender or CDC referral compensation for your financing transaction. Current SBA program rules should be verified with SBA and the professionals involved in your transaction.